
Specialist Roofing Insurance.
Operating a roofing firm involves managing severe operational hazards, including extreme height exposures, open flames, and structural alterations. Obtaining comprehensive roofing insurance provides vital financial security against third-party property damage, operative injury claims, and costly project disruptions. Standard commercial policies frequently fall short because they contain strict height exclusions or outright bans on heat application. A tailored insurance programme addresses these sector risks directly, protecting your balance sheet whilst ensuring full contractual compliance across high-risk commercial and residential worksites.
Inadequate policy conditions can instantly void coverage following a major worksite fire or height incident. Roofing contractors frequently face undisclosed warranty breaches regarding torch-on operations, sub-contractor checks, or unverified height thresholds that leave their businesses fully exposed to catastrophic compensation claims. How can roofing contractors structure their specialist insurance coverage to eliminate dangerous protection gaps and satisfy complex site requirements?
Key Takeaways
- Public liability insurance for roofers must account for height exposure and hot works activities to ensure complete financial protection during site operations.
- Strict hot works warranties require continuous sixty-minute fire watches and accessible fire extinguishers whenever torch-on felt application occurs on site.
- Standard liability policies often cap working heights at ten metres, requiring an explicit unrestricted height endorsement for higher structural contracts.
- Employers’ liability insurance remains mandatory under the Employers’ Liability (Compulsory Insurance) Act 1969 for all businesses employing direct or labour-only staff.
- Stripping older roofing materials requires specialist asbestos liability endorsements to cover accidental fibre exposure under the Control of Asbestos Regulations 2012.
Core Policy Components for Modern Roofing Contractors
Roofing contractors operate in a high-hazard environment that requires precise contractual risk transfer and broad insurance protection. Securing an adequate coverage schedule involves balancing standard public and employers liability policies with trade-specific endorsements. Brokers must evaluate project scopes carefully to align policy terms with modern building contracts and site health regulations.
Underwriters evaluate roofing risks based on height limits, hot works frequency, and subcontractor management protocols. The table below outlines the core insurance covers required across the UK roofing sector, detailing standard market indemnity limits, primary statutory drivers, and common policy conditions that contractors must maintain.
| Policy Coverage Type | Standard Market Limit | Primary Operational Focus |
|---|---|---|
| Public Liability | £2m, £5m, or £10m | Third-party property damage and personal injury claims |
| Employers’ Liability | £10m (£5m statutory minimum) | Workplace injury compensation under the 1969 Act |
| Contractors All Risks | Project contract value | Physical damage to works in progress and site materials |
| Plant & Equipment | Replacement value | Owned and hired-in machinery under CPA conditions |
| Hot Works Extension | Match PL limit | Fire watch warranties and permit-to-work compliance |
| Asbestos Endorsement | £5m or £10m sub-limit | Accidental disturbance during re-roofing operations |

Public Liability and Core Risks for Roofers
Essential Third-Party Liability Protections
Public liability insurance for roofers protects contractors against third-party property damage and personal injury claims arising from site operations. Falling debris, dropped tools, or water ingress during roof stripping can generate massive financial liabilities. Maintaining appropriate indemnity limits ensures financial protection when unexpected site accidents cause substantial external losses.
Main contractors routinely mandate public liability limits of five million or ten million pounds prior to contract award. Lower indemnity limits of two million pounds may suit minor domestic repairs, but larger commercial schemes demand higher thresholds. Policyholders must verify that their public liability wording extends to cover temporary weather-proofing failures. Sudden storms can cause interior water damage if open roofs are left unsecured overnight.
Subcontractor Flow-Down and Site Requirements
Roofing firms frequently deploy bona-fide subcontractors and labour-only operatives to complete complex projects. Insurers require strict risk management protocols, including verified subcontractor insurance checks. Failing to confirm that subcontractors maintain adequate liability cover can trigger policy warranties, leaving the primary roofing contractor responsible for third-party damage claims.
Contractors must maintain written records of subcontractor policy schedules and indemnity limits. Subcontractor flow-down clauses in main contracts typically require sub-contracted teams to match the primary contract terms. Insurers usually specify that bona-fide subcontractors must carry equivalent public liability limits. A lack of sub-contractor checking procedures will jeopardise policy indemnity during serious liability disputes.
Heat Application Risks and Hot Works Warranties
Heat Application Protocols and Fire Watch Conditions
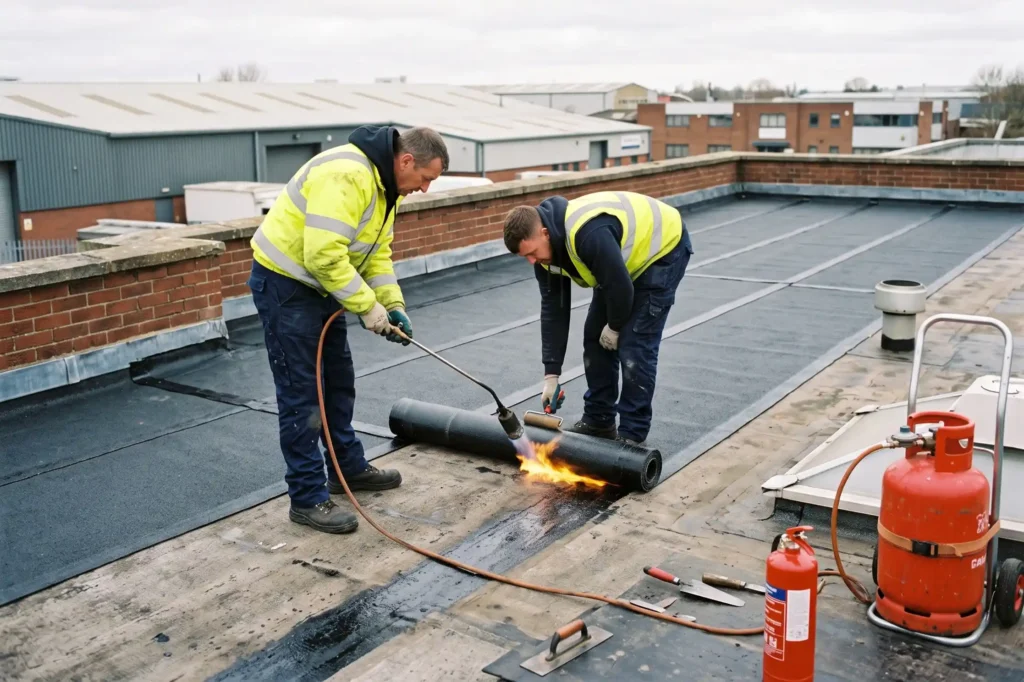
Torch-on felt applications present severe fire hazards, making hot works extensions a vital element of roofer insurance schedules. Insurers apply strict warranties governing open flame use, requiring continuous fire watches following heat application. Breach of these policy terms will completely invalidate fire damage claims, creating disastrous corporate financial exposures.
A standard hot work warranty mandates a thorough fire watch lasting at least sixty minutes after extinguishing all naked flames. Operatives must check roof voids, joists, and surrounding structures for smouldering materials using thermal imaging equipment or physical inspections. Hot works must cease at least one hour before operatives leave the job site. Non-compliance with fire watch timing remains a leading cause of rejected commercial property insurance claims.
Extinguisher Provision and Permit Enforcement
Insurers mandate formal permit-to-work systems for all roofing operations involving gas torches, hot bitumen, or grinding equipment. Operatives must clear combustible debris within a designated radius before applying heat. Additionally, suitable fire extinguishers must be positioned immediately adjacent to working areas to suppress accidental ignitions before fires spread.
Policies usually require two operational dry powder or foam fire extinguishers near every active burner. A designated safety officer must issue and sign off the written hot work permit before torching commences. Modern cold-applied liquid membranes or EPDM single-ply systems reduce fire risks significantly. Alternative cold roofing methods can lower insurance premiums by eliminating open flame liabilities entirely.
Did You Know?
The Health and Safety Executive can fine employers up to £2,500 for every day they operate without valid employers’ liability insurance, and up to £1,000 for failing to display a current certificate on request.
Work at Height Regulations and Height Limit Endorsements
Height Bands and Unrestricted Height Cover
Standard commercial policies often cap working heights at ten or fifteen metres above ground level. Roofers operating on multi-storey commercial buildings or high-rise residential blocks require explicit unrestricted height endorsements. Working beyond declared policy height limits without broker notification will result in an immediate denial of third-party liability cover.
Underwriters establish premium rates based on maximum operational heights and job locations. Contractors must disclose their deepest exposure levels during annual policy negotiations. High-level cladding, rainscreen installation, and structural roof repairs demand full transparency regarding access equipment. Specialist height endorsements eliminate restrictive height caps, enabling roofers to bid on major commercial contracts with confidence.
Statutory Compliance Under Height Regulations
The Work at Height Regulations 2005 impose legal duties on contractors to plan, organise, and supervise all elevated work. Insurers expect full compliance with statutory safety standards, including proper edge protection, scaffolding, and harness systems. Evidence of regulatory non-compliance during an incident can severely weaken legal defence arguments against third-party claims.
Roofing site managers must complete comprehensive Risk Assessments and Method Statements (RAMS) before starting work. Scaffolding must comply with NASC TG20 safety guidance and undergo weekly inspections. Operatives working on fragile roof surfaces must use crawler boards and safety nets. Adhering strictly to HSE guidance mitigates physical injuries whilst preserving policy protection during liability investigations.
Cover Built for Demanding Businesses
Across high risk industries, the cover we arrange most often includes:
Public liability
Employers' liability
Motor fleet
Contractors' all risks
Freight liability
Professional indemnity
Environmental liability
Business interruption
Most businesses need a combination, rather than a single focus policy, and we build cover around your contracts, your workforce and your operational activities.
Asbestos Exposure During Roof Stripping Operations
Duty to Manage Under Asbestos Regulations
Stripping older industrial or residential roofs often exposes workers to asbestos cement tiles, soffits, or insulation materials. The Control of Asbestos Regulations 2012 require contractors to identify hazardous materials before commencing structural work. Unintentional asbestos disturbance creates long-term health liabilities that standard public liability insurance schedules frequently exclude without specific endorsements.
Refurbishment and demolition asbestos surveys must take place prior to disturbing pre-2000 building structures. Roofing operatives must hold appropriate UKATA or equivalent asbestos awareness training certificates. If asbestos materials are discovered unexpectedly, work must stop immediately until qualified specialists assess the hazard. Proper site survey procedures prevent environmental contamination and expensive enforcement actions.
Specialist Endorsements for Asbestos Removal Work
Roofers performing non-licensed asbestos work require specific policy extensions to cover accidental fibre release and disposal liability. General liability wordings routinely contain absolute asbestos exclusions that remove all cover for related claims. Specialist roofing insurance policies include tailored asbestos extensions, ensuring protection when stripping chrysotile roofing sheets under regulated safety protocols.
Notifiable Non-Licensed Work (NNLW) requires formal notification to the HSE and strict health surveillance for operatives. Waste materials must be double-bagged, clearly labelled, and transported in accordance with the Hazardous Waste Regulations 2005. Insurers evaluate disposal manifests and consignment notes during loss adjusting. Maintaining full statutory compliance ensures that environmental liability extensions respond effectively to claims.
Employers’ Liability and Operative Safety Compliance
Statutory Obligations Under the 1969 Act
Employers’ liability insurance is a statutory requirement under the Employers’ Liability (Compulsory Insurance) Act 1969 for UK roofing firms. Employers must maintain a minimum indemnity limit of five million pounds, although market norms routinely provide ten million pounds. This policy covers financial liabilities arising from employee illness or injury caused by workplace negligence.
Roofing operations feature elevated risks of falls from height, structural collapses, and manual handling injuries. Statutory failure to hold valid employers’ liability cover carries severe financial penalties from the HSE. Certificates of insurance must be accessible to workforce members and displayed digitally or on-site. Brokers ensure that policies remain fully active to protect against catastrophic employee compensation demands.
Subcontractors, Labour-Only Teams, and Policy Limits
Distinguishing between labour-only subcontractors and bona-fide subcontractors is essential when structuring employers’ liability protection. Labour-only operatives work under direct supervision using the main contractor’s materials and tools, making them statutory employees under insurance law. Failing to declare labour-only headcount accurately during policy disclosures will create severe underwriting breaches during claims investigations.
Underwriters audit annual wage-roll declarations to calculate exact employers’ liability premiums. Bona-fide subcontractors work independently, set their own methods, and supply their own materials. Roofing contractors must check that bona-fide subcontractors carry separate public and employers liability policies. Misclassifying direct staff as bona-fide sub-contractors risks severe premium adjustments and policy voidance following operative accidents.
Contract Works, Plant, and Tool Coverage Structures
Contractors All Risks for Unfinished Works
Contractors All Risks (CAR) insurance provides vital material damage protection for incomplete roofing works, site materials, and temporary structures. Unforeseen events such as severe storm damage, vandalism, or site fires can destroy ongoing installations prior to formal client handover. CAR policies cover re-instatement costs, securing project cash flow against sudden physical losses.
Main building contracts such as JCT Design and Build frequently mandate joint-names CAR policies. Joint-names clauses protect both the main contractor and client under a single contract works schedule. Policy limits must align with maximum single contract values including free-issue materials. Arranging CAR cover on an annual basis offers broad security across multiple concurrent roofing sites.
Owned and Hired-In Plant Under CPA Conditions
Roofing operations depend heavily on specialised plant equipment, including tile hoists, cherry pickers, and mobile cranes. Plant insurance covers owned machinery against accidental damage or theft across operational sites. Hired-in plant protection covers contractual liabilities assumed under Construction Plant-hire Association (CPA) model conditions, including continuing hire charges during repair periods.
CPA hire terms transfer full risk of loss or damage to the hiring roofing contractor. Continuing hire charges accumulate rapidly whilst damaged lifting machinery undergoes repair. Plant schedules must specify appropriate indemnity limits for both owned inventory and hired equipment. Regular statutory inspections under LOLER 1998 remain mandatory for all lifting machinery operated on sites.
Fleet Management and Mobile Equipment Logistics
Commercial Motor Fleet Insurance Protocols
Operating multiple commercial vehicles requires a consolidated motor fleet policy to ensure continuous road legality under the Road Traffic Act 1988. Comprehensive fleet insurance covers vans, tippers, and flatbed lorries under a single manageable renewal date. Flexibility in driver entitlements helps roofing contractors manage staff movements efficiently across dynamic regional work sites.
Fleet pricing depends on historical claims experience, vehicle security measures, and driver age profiles. Implementing telematics systems helps monitor driver behaviour, reducing accident frequency across the vehicle fleet. Regular DVLA licence checks ensure that all operatives maintain valid driving credentials. Active fleet management lowers overall operational overheads whilst maintaining compliance with vehicle safety regulations.
Goods in Transit and Secure Tool Storage
Roofing tools, specialised equipment, and raw materials stored inside commercial vehicles face persistent theft threats. Goods in transit insurance covers expensive hand tools, gas burners, and raw materials during transport between depots and sites. Policies usually incorporate strict overnight vehicle security warranties requiring locked doors, immobilisers, or secure off-street parking.
Theft of tradesmen’s tools from unattended vans causes costly project delays and equipment replacement expenses. Insurers frequently impose overnight tool theft exclusions unless vehicles are parked inside secure compound facilities or fitted with approved alarms. Tools left inside vehicles overnight must be hidden from view in locked compartments. Selecting specialised hand tool extensions guarantees financial recovery following opportunistic site or vehicle break-ins.
Final Thoughts
Securing tailored roofing insurance requires a thorough understanding of operational hazards, contract terms, and underwriting conditions. Addressing hot works protocols, height limits, and sub-contractor checks eliminates protection gaps before losses occur on active sites. Structuring an integrated insurance schedule protects company cash flow, satisfies client requirements, and maintains compliance across all roofing operations.
Forward-looking roofing firms regularly review policy terms alongside operational growth to maintain appropriate liability limits. Evolving building regulations, emerging roofing technologies, and higher contractual demands require ongoing evaluation of policy schedules. Working closely with knowledgeable risk advisors ensures long-term operational resilience across complex commercial and residential projects.
Speak to an Insurance Specialist
Whether you need a new quote, want to discuss your renewal or have a question about an existing policy, our team is here to help.
Frequently Asked Questions
Q: Why do standard public liability policies exclude torch-on roofing operations?
A: Standard public liability policies often exclude torch-on roofing due to severe fire risks associated with open gas flames on dry timber or bitumen structures. Torch-on operations generate frequent high-severity fire claims, prompting standard underwriters to restrict heat application. Roofing contractors must obtain explicit hot works extensions that outline specific fire safety conditions, such as mandatory fire watches and adjacent extinguisher requirements. Without these tailored endorsements, any fire loss originating from flame application will be excluded from policy indemnity.
Q: What height limits apply to standard roofing insurance schedules?
A: Standard commercial liability policies typically apply a height restriction capping work at ten or fifteen metres above ground level. Operating beyond these declared limits without prior insurer approval will void coverage during a major loss event. Specialist roofer policies can provide unrestricted height extensions or higher customised height bands to accommodate multi-storey commercial cladding and high-rise roof replacement contracts. Contractors must review maximum contract working heights annually with their broker to maintain valid policy terms across all active sites.
Q: Are roofing contractors required to carry asbestos liability cover?
A: Roofing contractors stripping older properties built prior to 2000 frequently encounter asbestos cement sheets, soffits, or flashing materials. Standard public liability policies contain absolute asbestos exclusions that remove coverage for accidental fibre disturbance or pollution claims. Contracting teams undertaking non-licensed asbestos removal require specialist asbestos liability extensions to protect against accidental exposure and waste disposal liabilities under the Control of Asbestos Regulations 2012. Maintaining survey records and operative training certificates ensures full policy protection during site work.
Q: What is the difference between direct employees and labour-only subcontractors?
A: Direct employees and labour-only subcontractors work under the supervision, direction, and control of the main contractor, using the firm’s tools and equipment. Under the Employers’ Liability (Compulsory Insurance) Act 1969, labour-only subcontractors are classified as statutory employees, requiring mandatory employers’ liability insurance. In contrast, bona-fide subcontractors operate independently, determine their own working methods, and provide their own materials. Roofing contractors must maintain separate records for labour-only wage rolls and confirm that bona-fide subcontractors carry independent public liability policies.
Q: What coverage does Contractors All Risks insurance provide for roofers?
A: Contractors All Risks (CAR) insurance covers physical damage to uncompleted roofing works, materials on site, and temporary structures caused by insured perils such as storm, fire, or vandalism. If extreme weather damages an open roof replacement scheme prior to practical completion, CAR insurance pays the re-instatement costs for damaged materials and labour. Main building contracts frequently require CAR cover on a joint-names basis with the property owner or principal contractor, protecting project finances against catastrophic physical loss events during construction.
About The Author
Darren Judd
Director, Co-Founder and Co-Owner of Capital Corporate Risks Ltd

Experienced Account Executive with a demonstrated history of working in the insurance industry. Skilled in Account Management, Risk Management, Business Development across all classes of insurance within the Construction Industry,